Loyalty
Act solely in the interest of the plan's participants and beneficiaries.
In practice: nobody advising the plan should have an interest in it costing more.
ERISA §404(a)(1)(A)
Fiduciary employee benefits consulting for employers who run on strategy.
You run every other part of your business on strategy. Your health plan gets a renewal meeting and another increase. Ethos Benefits is the employee benefits consultant that accepts fiduciary responsibility for its advice on your health plan, in writing, keeps the record that proves it, and builds a plan that does more for your people and costs your company less.
Listed exactly as awarded, with who won each one. Every award and all the press coverage
 Fiduciary Validation, Benefits FirmEthos Benefits. Validation Institute.
 Advisor of the Year, Health Value AwardsDonovan and Chelsea Ryckis, two of twelve Charter Fiduciary Advisors. Validation Institute.
 Cover story, bip MagazineDonovan and Chelsea Ryckis. NABIP, Spring 2025.
 Advisor of the YearChelsea Ryckis. BenefitsPRO.
 Most Innovative Healthcare ConsultantDonovan Ryckis, 2026. Chelsea Ryckis, 2024.
Your 401(k) has a committee, minutes, benchmarking and an advisor who signs a fiduciary acknowledgment. Your health plan is the larger and less predictable spend, and it has a renewal meeting. ERISA does not distinguish between the two: if you sponsor the plan and make decisions about it, you are a fiduciary of it. ERISA §3(21)(A).
The duty is the reason to run the health plan the way you already run the retirement plan, and to expect the people advising you to share it.
What the duty requiresSame duty, two plans
How these plans are typically run.
Your retirement plan has always been held to these ERISA fiduciary duties. Here they are in plain language, with the section of ERISA that says so.
Act solely in the interest of the plan's participants and beneficiaries.
In practice: nobody advising the plan should have an interest in it costing more.
ERISA §404(a)(1)(A)
Act with the care, skill and diligence a knowledgeable person would use.
In practice: document the alternatives, benchmark the vendors, read the claims, keep minutes.
ERISA §404(a)(1)(B)
Run the plan according to the documents that govern it.
In practice: the plan document, the SPD and the vendor contracts agree, and the plan does what they say.
ERISA §404(a)(1)(D)
| What the plan needs | A typical employee benefits broker | Ethos Benefits |
|---|---|---|
| Fiduciary responsibility for health plan advice | Usually declined in the agreement | Accepted in writing |
| The renewal | The carrier's quote | Alternatives documented and benchmarked |
| Claims and pharmacy data | The carrier's summary | Read directly |
| Vendor contracts | Reviewed at renewal, if at all | Reviewed on a schedule |
| The decision record | Email threads | Committee minutes, kept in one place |
How these roles typically work.
Your engagement runs the same five phases, in order. We take your plan apart and put it back together, and each phase teaches you something about your own plan before anything is changed.
Your plan is served by an Ethos Benefits client team of account executives and account managers, led by these executives. Every benefits advisor on that team works to a fiduciary standard of care. Your current benefit advisor can sign the same acknowledgment. If the answer is a paragraph, you have your answer.

Founder and CEO
2026 Advisor of the Year, Validation Institute. 2026 Most Innovative Healthcare Consultant, YouPowered Symposium. Former Series 65 investment advisor.

Founder and President
2026 Advisor of the Year, Validation Institute. 2024 Advisor of the Year, BenefitsPRO. 2024 Most Innovative Healthcare Consultant, YouPowered Symposium.

Partner and Director of Client Operations
Runs the Ethos Experience: the standing client call, the committee record and the service calendar.
Your plan has its own starting point. These employers' published case studies show what changed for their companies and their people.
HVAC, 400 employees
42%lower healthcare cost. Over $13.5 million saved.
One delivery: the hospital pre-authorized $37,594, the plan paid $18,000, and the employee paid nothing.
Read the Kalos case studySenior living, 1,000 employees
27 to38%lower employee premiums, depending on the plan.
Plan redesign moved cost off employees without moving it onto the employer.
Read the Axiom case studyShipyard, 300 employees
77%below billed charges on $50.4 million in claims over five years.
A self-funded plan with reference-based pricing paid $11.4 million.
Read the Hendry Marine case studyFigures as published in Ethos Benefits case studies, with client permission.
The reality is, if this industry worked well, there’d be no need for Cost Plus Drugs. There’d be no need for Ethos… We’re here because of the information asymmetry.
Mark CubanFounder, Mark Cuban Cost Plus Drug Company. On Business of Benefits, Episode 75.Watch the episode
The numbers spoke for themselves. We were able to lower deductibles and decrease employee premiums by 27 to 38% depending on the plan. The service we’re getting from Donovan and his team is just tremendous.
Brenda KruseCFO, Axiom Healthcare ServicesRead the Axiom case study
There’s no legal requirement for them to act in your best interest. And once you understand that… everything starts to make sense.
Bryan OrrPresident and Co-Founder, Kalos ServicesRead the Kalos case study
I said there is absolutely no way, you guys are nuts, and it sounds too good to be true. So I decided that I needed to learn. We took an EOB from one of my employees, ran it through what it would be through reference-based pricing, and the light bulb went on.
Stephanie PorrinoFormer HR Director, Hendry Marine IndustriesRead the Hendry Marine case study
Your benefits get the same plan as the rest of your business: three to five years out, measured every quarter. Your committee sets the goals and tracks the numbers against them. Ethos builds the plan with you, reports against it and keeps the record of every decision.
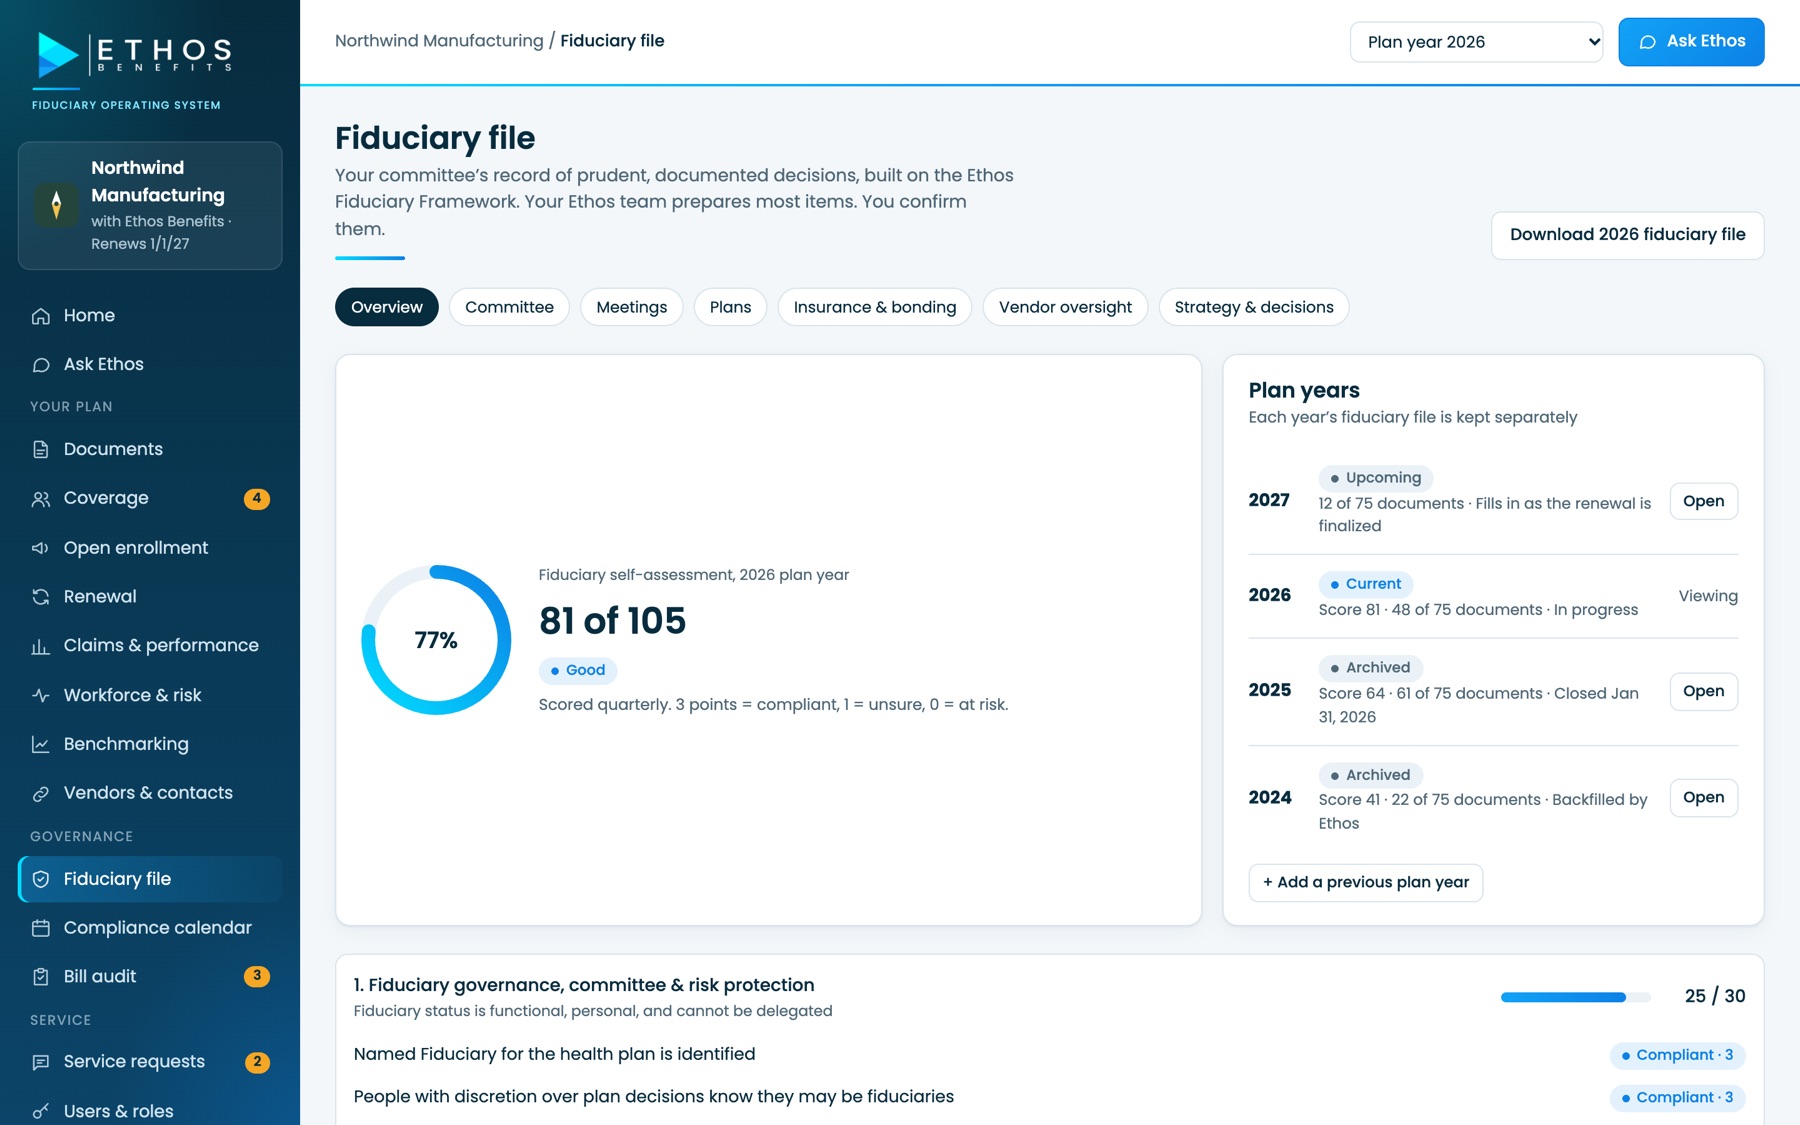
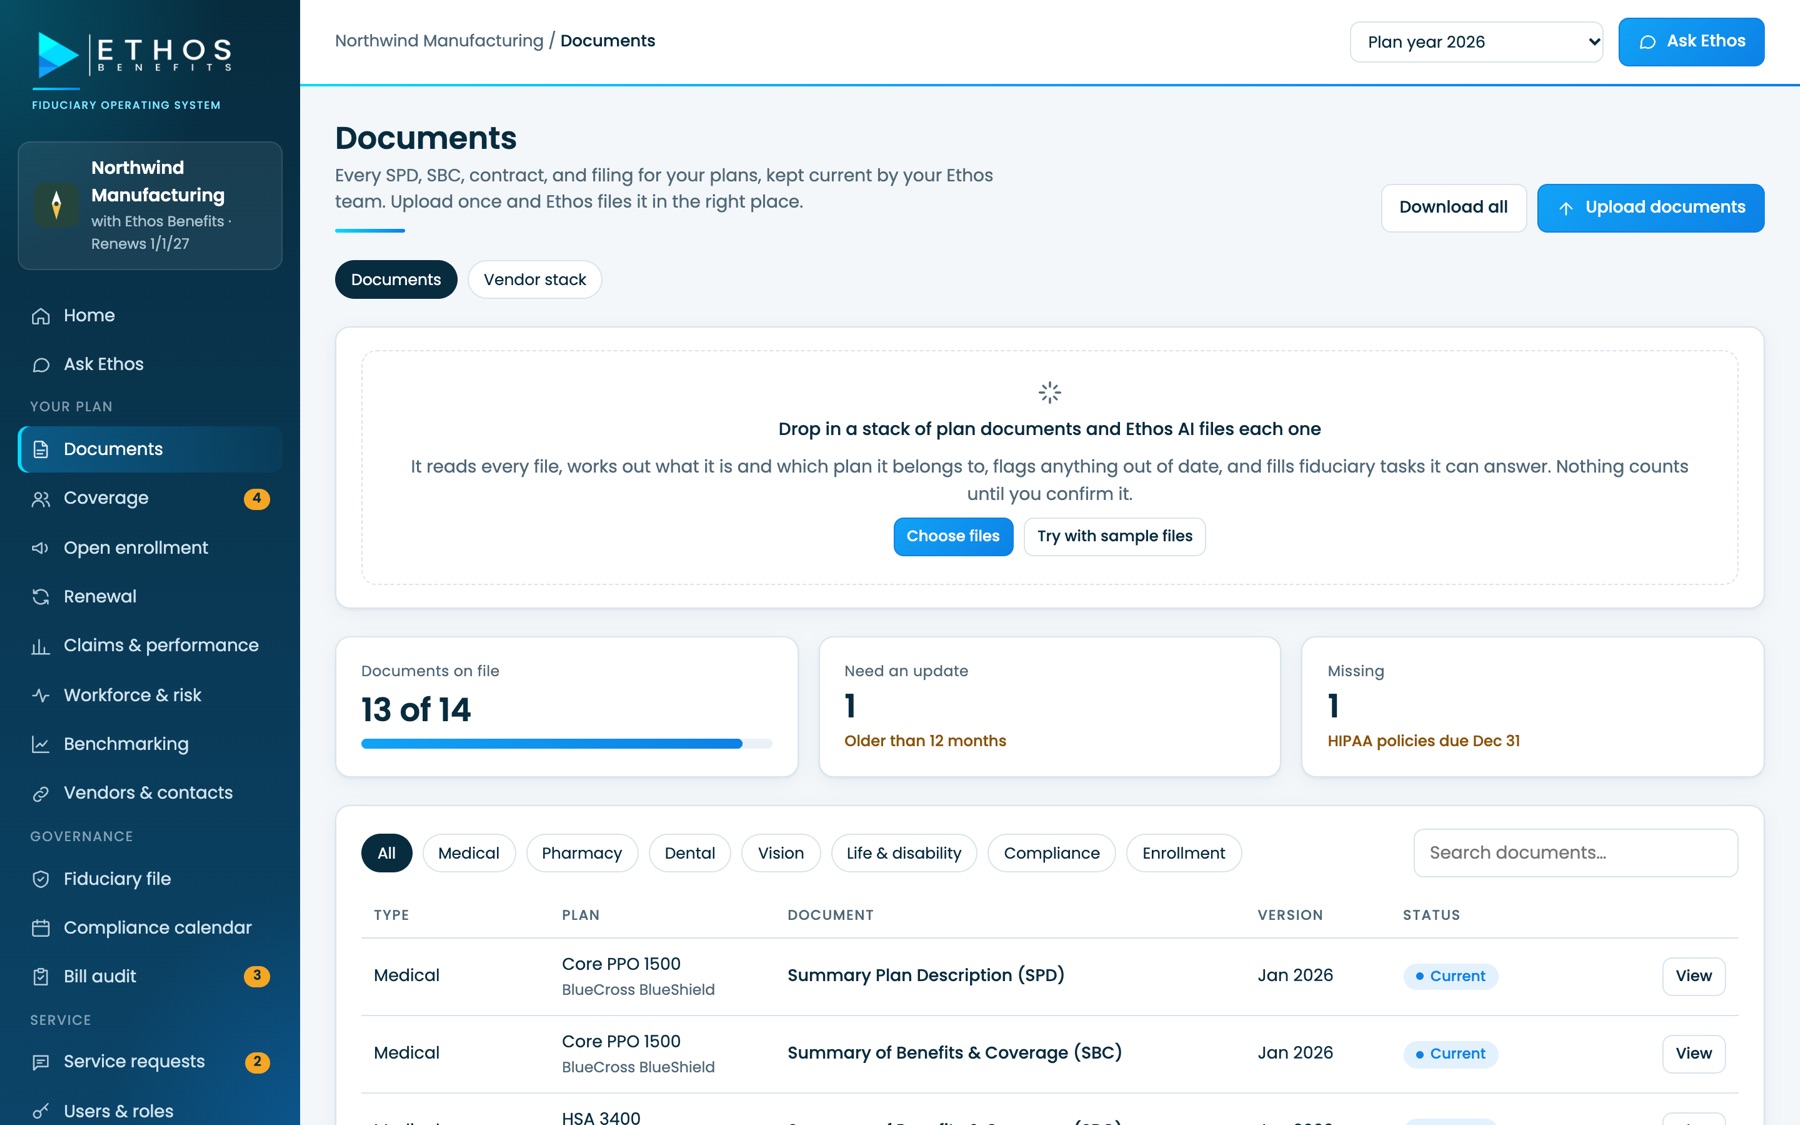
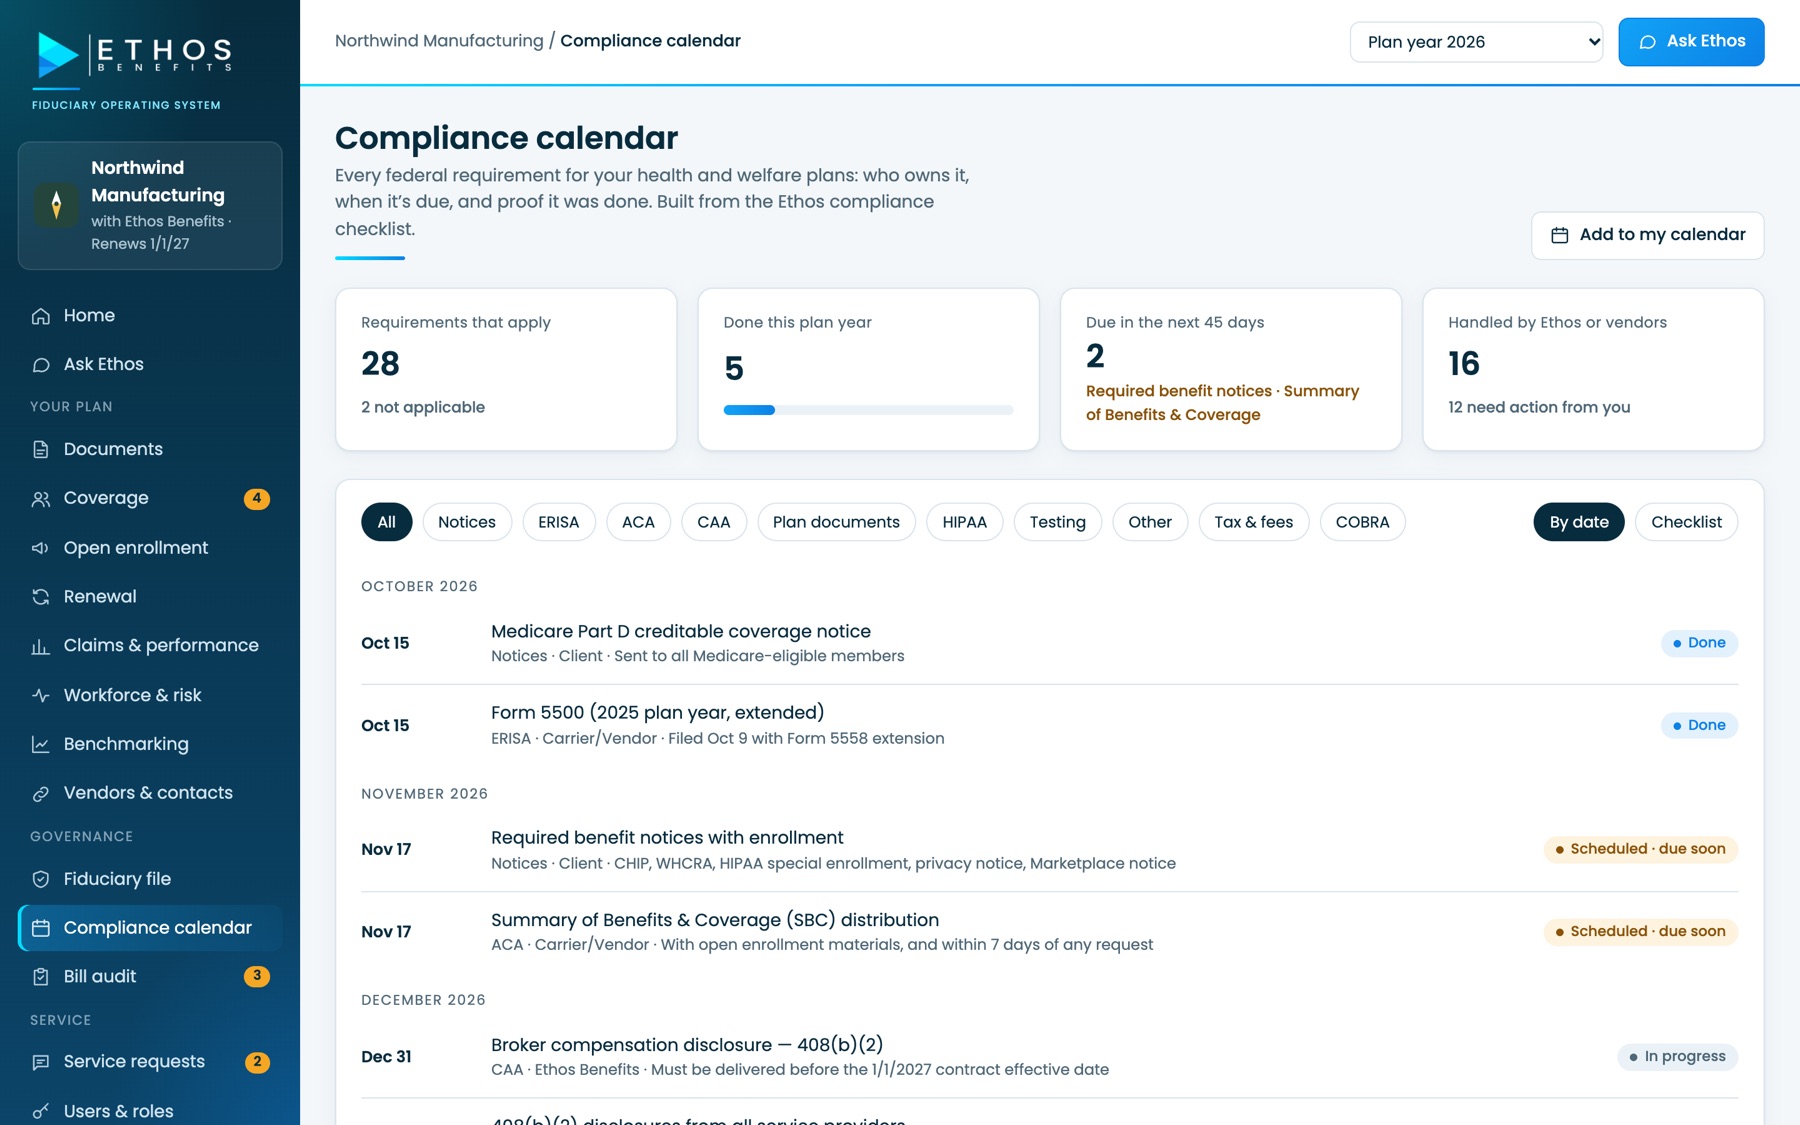
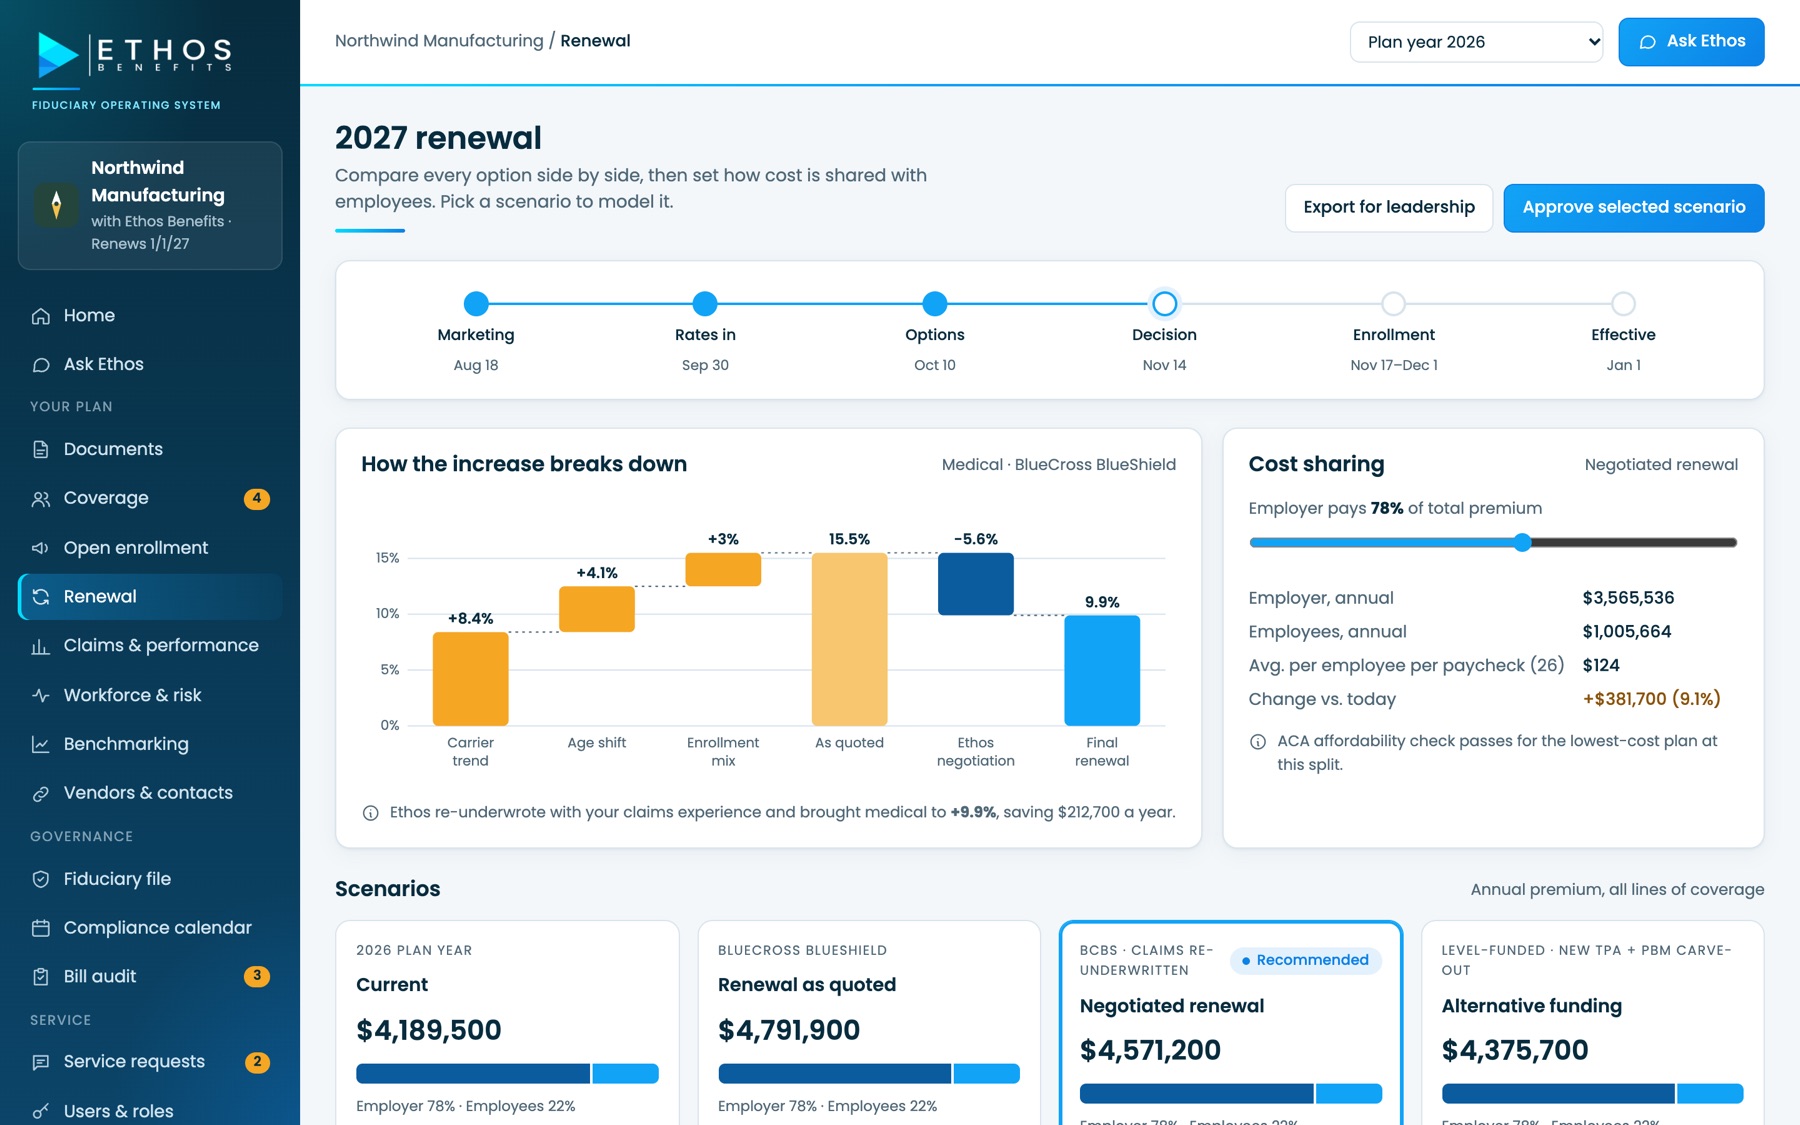
Most benefits programs run on inboxes, last year's deck and a renewal call. Your Ethos team keeps every file, number and decision about your plan in the Ethos Fiduciary OS, in one place, year after year, and you can ask it anything. Tour the Fiduciary OS
Today. Files in inboxes, KPIs in last year's deck, no trend line and no benchmark.
With Ethos. Every file, KPI, benchmark and trend in one place, kept for every plan year.
Today. The renewal is decided on a call, and the reasoning is never written down.
With Ethos. A formal review and decision process, with the reasoning in your fiduciary file.
Today. Plan questions mean digging through PDFs or waiting a day for your broker.
With Ethos. Ask any plan question across every line of coverage and get the cited answer. Coming soon
Portal screens show a sample company and sample figures, not client results. Features marked Coming soon are in development.
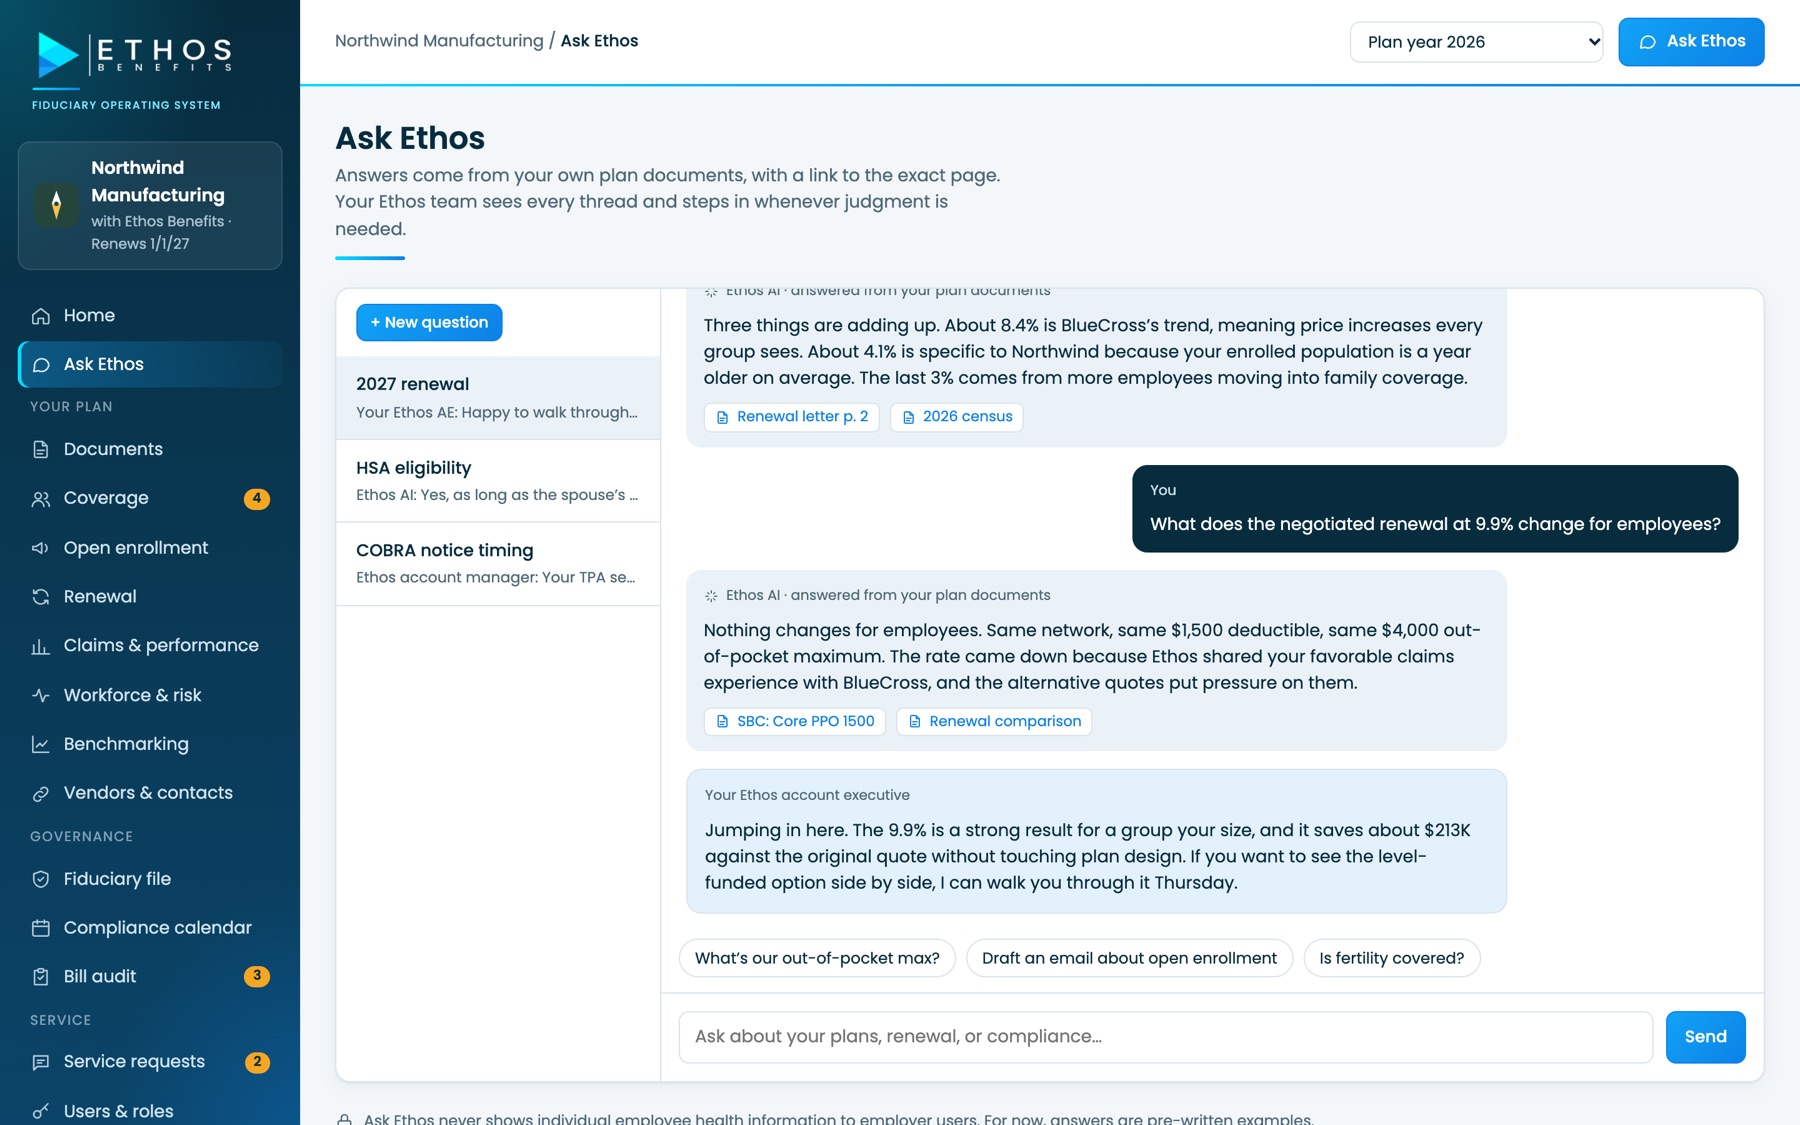
Your team can understand how the plan is priced whether or not you hire us. Chelsea and Donovan Ryckis and their guests cover what employers pay for health plans, who benefits, and how to change it. Real cases, real numbers, no sales pitch.
Every episode on YouTube · Episode notes and transcripts
Your committee gets plain-English guides to the rules and the money behind an employer health plan, each with its sources, and the newest analysis as we publish it.
If you sponsor an ERISA-covered plan and make decisions about it, yes. ERISA §3(21) defines a fiduciary by function, not title.
Usually not, and usually by contract. Most agreements state the firm is not a fiduciary. Ethos provides a signed acknowledgment in its engagement agreement.
Alternatives documented, vendors benchmarked, compensation disclosures reviewed, claims read directly, and a committee decision with minutes.
A broker places coverage and usually declines fiduciary responsibility in the agreement. An employee benefits consultant like Ethos Benefits accepts fiduciary responsibility for its advice on your health plan, in writing, and documents the alternatives, the benchmarks and the decision.
Ethos Benefits provides fiduciary governance for your health plan: a committee charter, documented vendor reviews and benchmarking, minutes and compliance deadlines, with fiduciary responsibility for its advice accepted in writing.
A fee for healthcare plan advice, agreed with you in writing, that does not change when your premium changes.
Your Strategic Analysis begins with your broker agreement and your plan documents, then the plan itself: what it costs, where the risk sits, and what a committee would decide with the full picture.
One email a month on what is changing in employer health plans, written for the person who signs the check.